Economy 5 min read By Arthur Ellington
Bessent Says Rising Treasury Yields Reflect Global Trend, Not Cause for Alarm
US Treasury Secretary Scott Bessent has dismissed concerns over rising long-term government bond yields, arguing they reflect a global shift in interest rates rather than a crisis of confidence in American fiscal policy. The 30-year Treasury yield has climbed above 5.6%, pushing up government borrowing costs and intensifying debate over the sustainability of US debt.
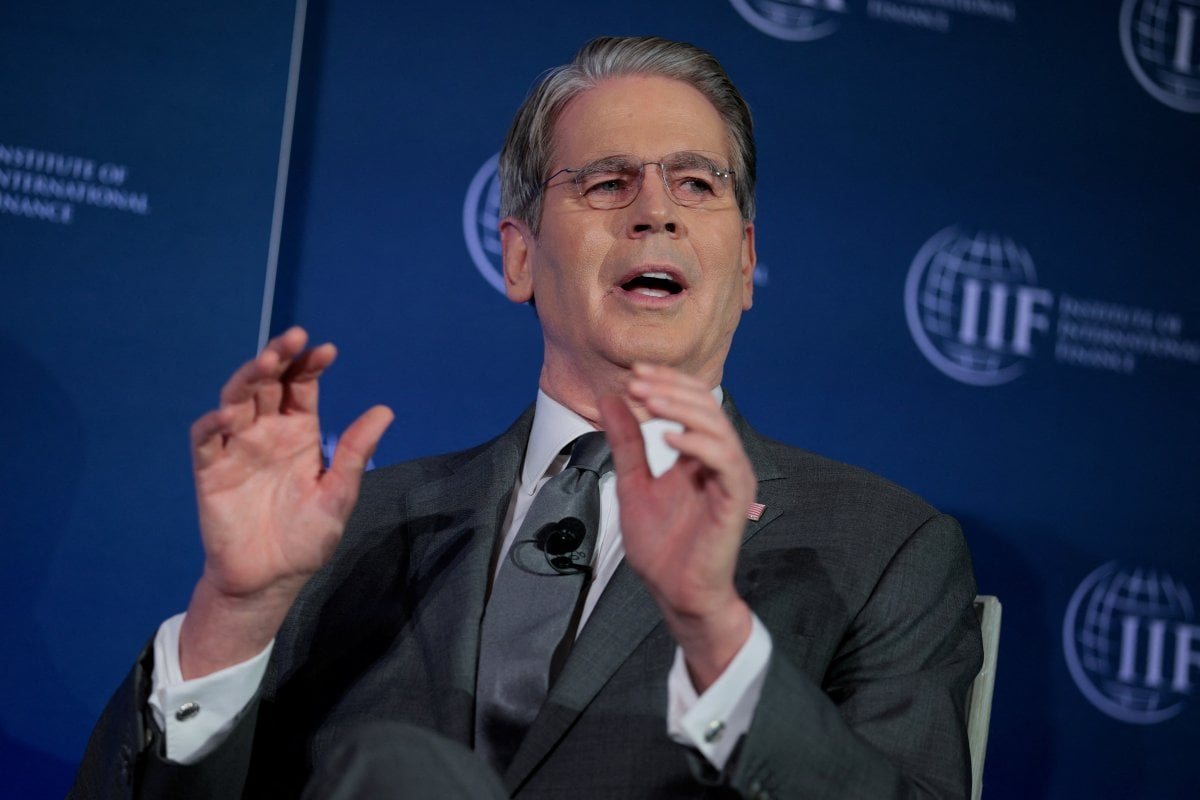
US Treasury Secretary Scott Bessent has pushed back against alarm over rising long-term government bond yields, saying the move reflects a broad global trend in interest rates rather than a loss of confidence in American fiscal policy. His remarks come as the 30-year Treasury yield trades above 5.6%, a level last seen in 2002, while the 10-year yield sits near 5.3%.
Bessent's intervention is significant because it sets the tone for how the Treasury Department views the sharp increase in borrowing costs at a time when the federal government is running deficits of around $1.9 trillion. The Congressional Budget Office projects those deficits will grow further, and the cost of servicing the national debt has already reached $857 billion over the first nine months of the fiscal year — more than the government spent on either Medicare or national defence over the same period.
The rise in yields is not simply a story about inflation expectations. Market data show the 30-year breakeven inflation rate, which measures the market's long-run inflation forecast, sits near 2.3%, an unremarkable level. Instead, the 30-year real yield — the inflation-adjusted return demanded by bondholders — has climbed above 3%, its highest level since before the 2008 financial crisis. That suggests investors still expect the dollar to hold its value reasonably well, but are demanding a higher real price for financing the government.
Analysts attribute much of the pressure to the competing demands of public borrowing and private investment. The artificial-intelligence buildout is requiring enormous sums for data centres, semiconductors and electric power, while the federal government continues to borrow heavily. When demand for savings outruns supply, the price of those savings — the real interest rate — rises. Some of this reflects a growing economy with productive investment opportunities, but deficits at the current scale risk crowding out the very investment that raises future living standards.
The arithmetic compounds. Higher yields raise debt-service costs, which widen deficits, which require still more borrowing at those same elevated yields. A sustained 3% long-term real yield signals that capital scarcity is binding again, a sharp break from the near-zero rates that prevailed between 2008 and 2020 and taught borrowers, Congress included, to treat capital as essentially free.
The Treasury's response has drawn scrutiny. In August, Bessent doubled the department's buybacks of 10- to 30-year debt after months of weak demand. Yields fell on the announcement but fully reversed within a day. A $4 billion operation cannot move a market measured in trillions, and improvised interventions risk undermining the «regular and predictable» issuance framework Bessent himself has championed. Debt management can smooth market liquidity, but it cannot create savings.
Krishna Guha, head of economics and central bank strategy at Evercore, has observed that struggling sovereigns often resort to such tactics, and that the United States «is not different without limit». The only durable solution, analysts argue, is to put fiscal policy on a sustainable trajectory through a combination of tax increases and spending cuts. On the tax side, room is limited: over the past 60 years, federal receipts have ranged between 14.4% and 19.8% of GDP, averaging 17.0%. Broadening the tax base by raising taxes on the middle class is politically unfeasible in the US, leaving spending restraint as the main lever.
The immediate goal, economists say, is to keep the growth rate of federal expenditure below the growth rate of the real economy, with modest tax increases smoothing the adjustment. The deeper lesson concerns fiscal discipline. Congress has repeatedly rejected budget rules, spending caps and entitlement reform, leaving bondholders as the only remaining check on federal borrowing. High bond yields are an information signal, and this one says the government's fiscal path is being repriced.
3