Business 3 min read By Bethany Hadley
Once Upon a Farm's $724m IPO was about more than growth, says Jennifer Garner
The actress and co-founder says the baby food company's listing hinged on what it chose to protect from the start, as investors weigh mission alongside scale.
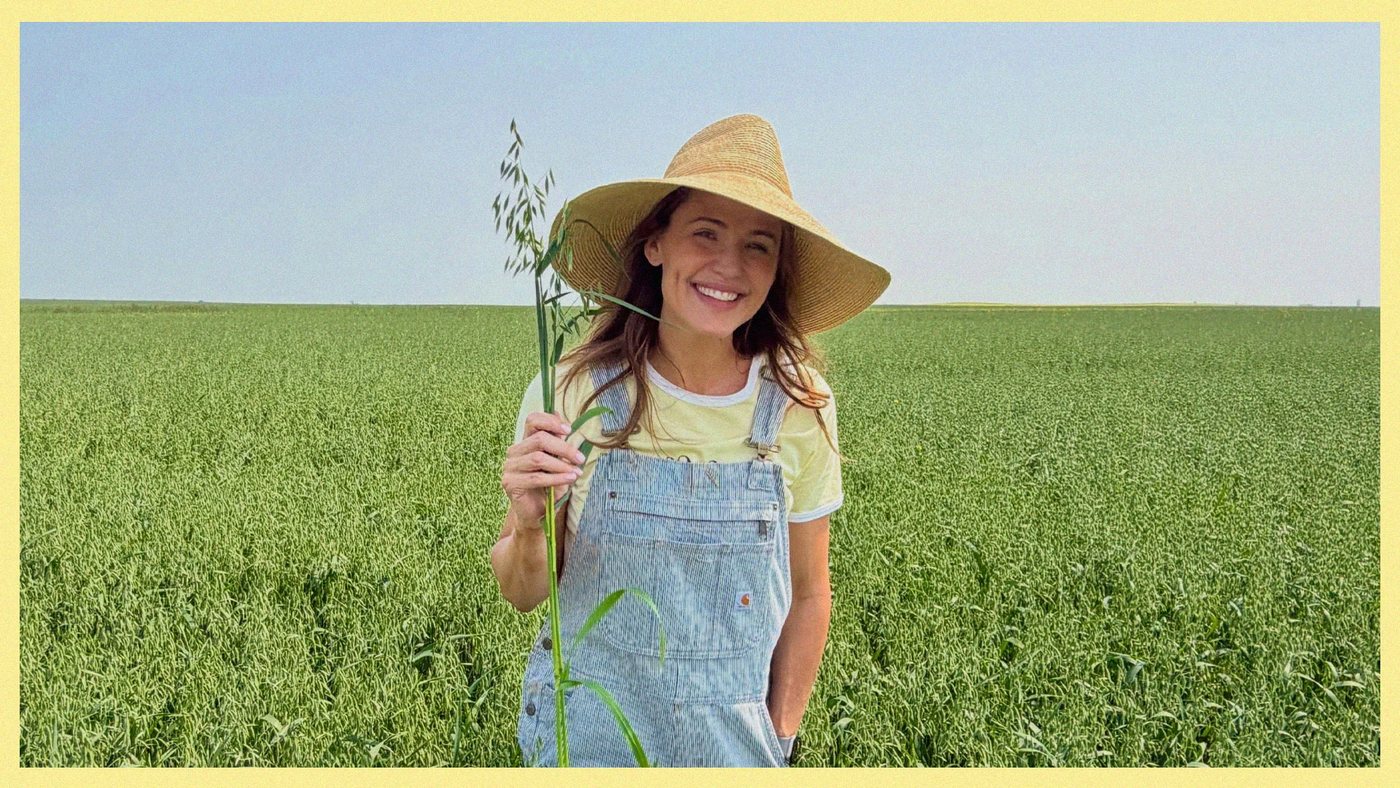
Once Upon a Farm's $724 million initial public offering was not simply a bet on growth, according to co-founder Jennifer Garner, who says the company's decision to protect its early standards shaped the way customers and investors now view the business.
The actress and entrepreneur, who founded the baby and children's food brand alongside chief executive Cassandra Curtis and others, has framed the listing as the outcome of a single question that guided the company from its earliest days: what should be preserved as the business scales. That question, she argues, determined not only the product but the expectations of the parents who buy it.
The company's market debut values the business at a level that places it among the more prominent consumer listings of the year, and it arrives as investors are paying closer attention to whether mission-led brands can hold their identity once they face public-market scrutiny. For Once Upon a Farm, the answer has been to treat its sourcing and nutrition standards as fixed points rather than variables to be traded away for margin.
Garner's argument is that this discipline is not a marketing posture but an operating constraint. It shapes which ingredients the company will use, which suppliers it will work with and which products it will decline to launch. In a category where parents scrutinise labels closely, that consistency becomes a commercial asset: it builds the trust that allows a brand to charge a premium and to keep customers as their children grow.
The listing also puts a spotlight on the role of founder-led storytelling in consumer businesses. Garner's public profile gives the company a reach that most food startups cannot buy, but her framing of the IPO suggests she sees the capital raised as a means of extending the founding promise rather than replacing it. The risk, as with any public company, is that quarterly reporting creates pressure to prioritise near-term numbers over the standards that built the brand.
For British readers watching the consumer and food sector, the Once Upon a Farm listing is a useful case study in how a company's early choices can become its long-term moat. It also illustrates a broader shift in how investors assess consumer brands: not only whether they can grow, but whether the thing that made them distinctive can survive the growth.
The company now faces the task of proving that its founding question can be answered repeatedly, in public, as it scales. Garner's account of the IPO suggests she believes the answer lies in what the business refuses to change, even as everything around it does.