Business 4 min read By Alice Ashford
Magnificent 7's cash advantage eroded by AI spending, warns Bank of America strategist
Michael Hartnett, who coined the term in 2023, says the tech giants' shift from cash generators to heavy borrowers ties their fortunes to the bond market, while political backlash poses a separate risk.
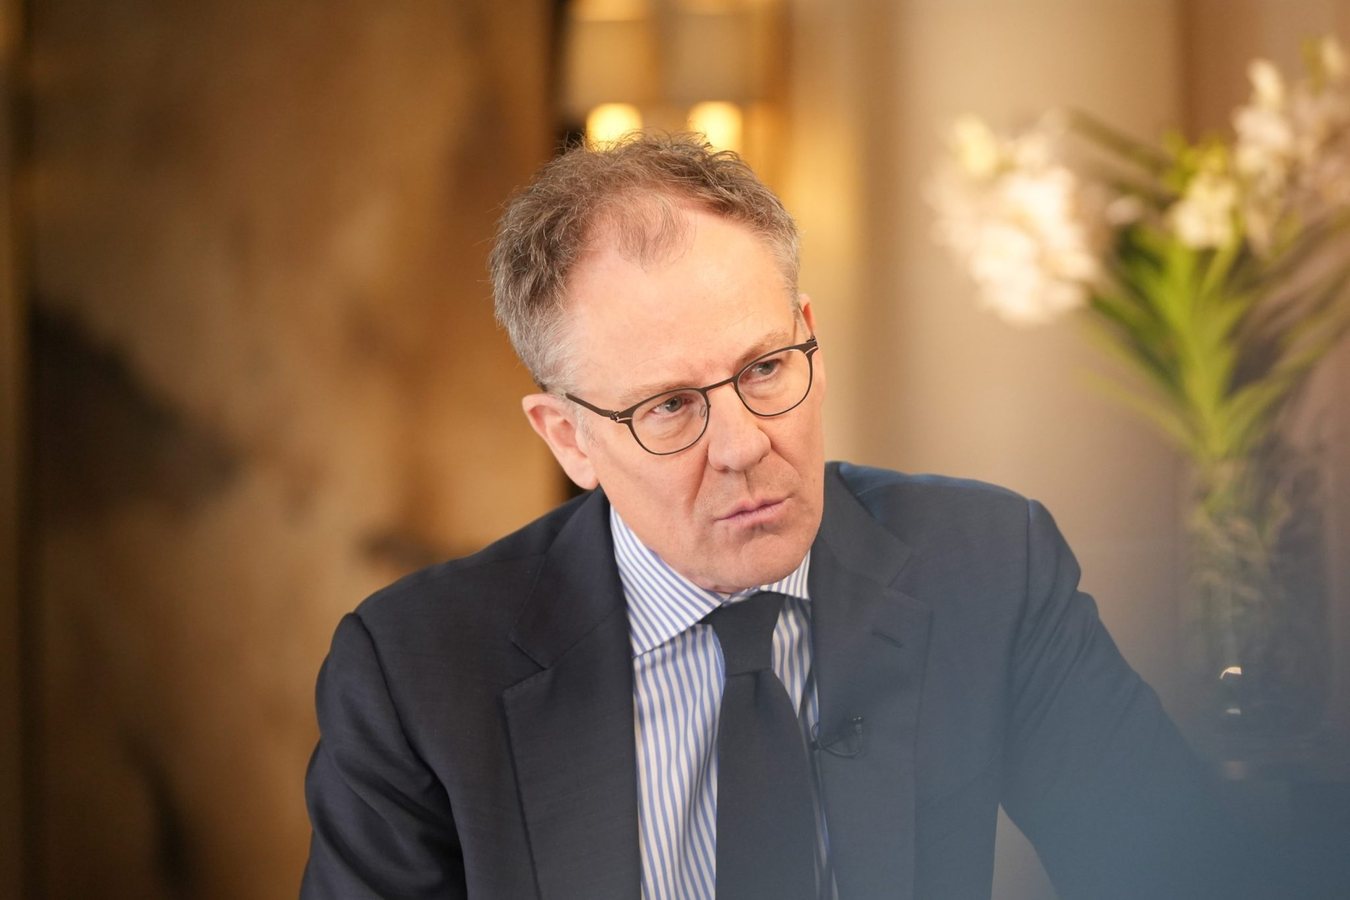
The group of American technology companies known as the Magnificent 7 is losing the defining characteristic that made it a must-own for investors, according to the Bank of America strategist who coined the term. Michael Hartnett, the bank's chief investment strategist, argues that the seven firms—Apple, Amazon, Alphabet, Meta, Microsoft, Nvidia and Tesla—built their reputation on generating vast amounts of cash while spending almost none of it. That is no longer the case.
Speaking on the Master Investor podcast, Hartnett explained that the rise of the Magnificent 7 was driven in part by investor disillusionment with government debt. «To a certain extent, the rise of the Mag 7 was because nobody wanted to hold government bonds,» he said. «I don't want the government balance sheet. They spend like drunken sailors. Why do I want to lend to them? I'd rather put my money with companies that have tons of cash and don't spend any of it.» That, he said, was the essence of the Magnificent 7's appeal.
Now those same companies are spending at a scale that has transformed their financial profile. Global AI investment is expected to exceed $1 trillion in 2026, according to Goldman Sachs, while JPMorgan Chase chief executive Jamie Dimon expects hyperscaler AI spending to reach that level next year. The technology sector has run down its cash reserves and begun borrowing heavily in corporate credit markets. Hartnett estimates that the hyperscalers are now spending more than a trillion dollars a year on AI capital expenditure while running negative cash flow of around $200 billion.
The consequence is that the Magnificent 7's prospects are increasingly tied to the very asset class they were once used to avoid. With 10-year Treasury yields near a two-decade high and 30-year yields above 5.5 per cent for the first time since 2002, borrowing costs across the economy have risen. «They have to be kind of subservient to the bond market,» Hartnett said. «If the bond market pushes up yields or spreads too much, you're not going to get the spending.»
Wall Street remains divided over US Treasury Secretary Scott Bessent's recent bond buyback scheme, but economists told Fortune the action taught investors an important lesson about the point at which the Treasury will intervene to smooth volatility. While the 5 per cent mark sticks in investors' minds, it has not automatically triggered action in the past. Hartnett noted that half of his job involves listening to smart clients and half involves watching market prices. «It's not me thinking 5 per cent is a magical level,» he said.
The threshold matters more to policymakers, Hartnett argues, because higher domestic yields would prevent AI companies from borrowing to fund capital expenditure and would damage the wealth effect that has been so strong through the equity market. Geopolitically, he added, there is a single objective: beating China in AI. A disorderly move in the bond market cannot be allowed, and he believes policymakers will succeed because they will do whatever they can to prevent it.
However, Hartnett draws a distinction between the threats facing Wall Street and those facing Main Street. «What they can't necessarily manipulate is if voters basically vote against AI,» he said. «So the Wall Street threat is bonds. The Main Street threat is voters.»
The Magnificent 7 remain dominant forces in the stock market, but their transformation from cash-rich holdouts into debt-dependent spenders marks a significant shift in the investment case that made them extraordinary. For British investors with exposure to US technology stocks, the message is that the group's fortunes now depend on borrowing conditions as much as on innovation.
4