Economy 5 min read By Alice Ashford
China's Treasury sell-off may mask stealth buying through Canada and Europe
Official U.S. data show China's Treasury holdings falling to an 18-year low of $591 billion, but analysts suspect Beijing is shifting debt to custodians in Canada, Belgium and elsewhere rather than dumping it outright.
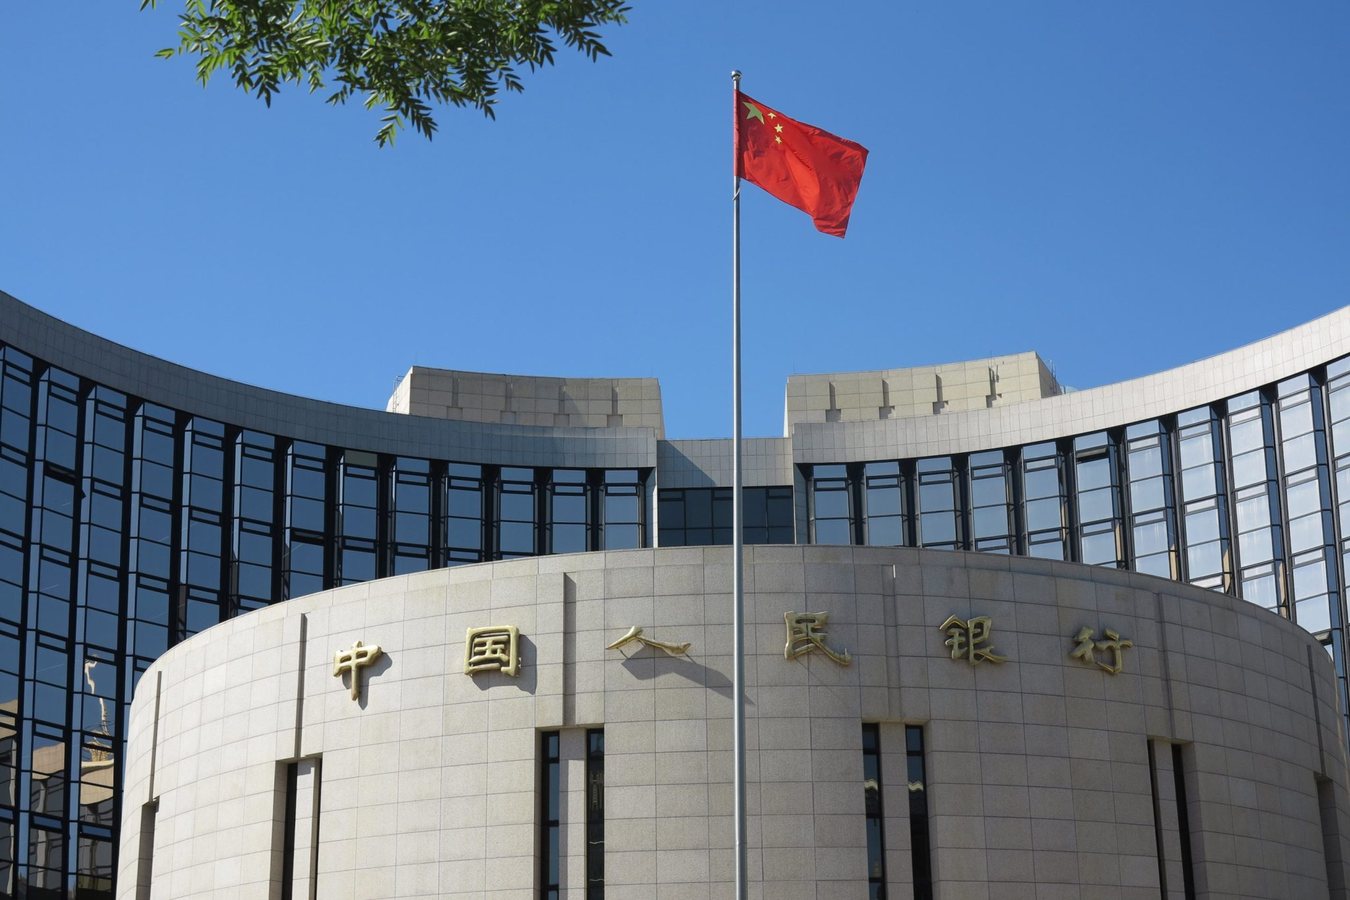
China's official holdings of U.S. Treasury securities have fallen to their lowest level in 18 years, but the decline may be less dramatic than it appears, with analysts pointing to suspicious jumps in Treasury stocks held in Canada and European custodial centres that suggest Beijing is quietly shifting assets rather than selling them outright.
U.S. data released on Friday show China held $591 billion in Treasury securities as of August, down from $700 billion a year earlier and far below the $1 trillion it held as recently as April 2022. The figures, collected primarily from U.S.-based custodians and broker-dealers, have fuelled years of speculation about de-dollarisation and a wholesale Chinese retreat from U.S. assets.
But the Treasury Department itself notes that securities held in overseas custody accounts may not be attributed to their actual owners. China watchers have long been sceptical of the headline numbers, pointing to sharp increases in holdings elsewhere that coincide with the Chinese decline. Canada's Treasury holdings soared to $465 billion in August from just $169 billion five years earlier, while Belgium's stockpile rose to $490.5 billion from $228 billion over the same period. Including bonds backed by federal housing agencies, the shifts are even larger.
Brad Setser, a senior fellow at the Council on Foreign Relations and a former Treasury official, said the evidence that China uses a Canadian custodian for some of its agency holdings is especially strong, citing the sudden jump in Canada's holdings and the impact of the detailed June survey. He has estimated that adding China's declared holdings to those in Canada and European custodial centres such as the United Kingdom, France, Luxembourg and Belgium produces a total as high as $500 billion. A narrower adjustment covering only Canada, Luxembourg and France since about 2022 still puts China's holdings at around $300 billion.
Setser estimated that China's total U.S. financial holdings remain between 50% and 55% of its reserve portfolio, even as Beijing has reduced long-term Treasuries in favour of short-term bills. He said both the Treasury and agency portfolios need to be adjusted for bonds China keeps in custody in Canada and Europe, adding that the use of multiple non-U.S. custodians makes the true figure harder to pin down.
The debate matters because China was once the largest foreign holder of U.S. government debt, and its retreat has been read as a signal of deepening financial rivalry between Washington and Beijing. China has been challenging U.S. supremacy in global finance and seeking to reduce the dollar's role as the world's top currency. U.S. sanctions against Russia after its 2022 invasion of Ukraine encouraged the People's Bank of China and other central banks to diversify reserves towards assets such as gold, while President Donald Trump's trade war gave Beijing further reason to decouple from U.S. markets.
Yet China's reliance on export-led growth has given it a powerful incentive to recycle its surpluses into dollar assets. The country posted a $1.2 trillion trade surplus in 2025, the largest in recorded history and growing three times faster than global goods trade. For the first nine months of 2026, the surplus reached $938 billion, with expectations growing that it could surpass last year's record. Such inflows must be reinvested somewhere, which analysts say may explain a shift towards non-U.S. custodian banks rather than an outright exit from Treasuries.
The upshot is that the official American data may understate China's true exposure to U.S. government debt, complicating assessments of both Beijing's de-dollarisation drive and the risks facing the Treasury market. For investors and policymakers, the lesson is that custody data reflects where securities are booked, not necessarily who owns them.
8