Business 3 min read By Arthur Ellington
Deckers Brands shares fall 8% after revenue miss despite raised profit guidance
Deckers Brands shares dropped 8% after the footwear group's quarterly revenue fell short of expectations, even as the company lifted its earnings guidance. The shortfall in sales overshadowed the improved profit outlook.
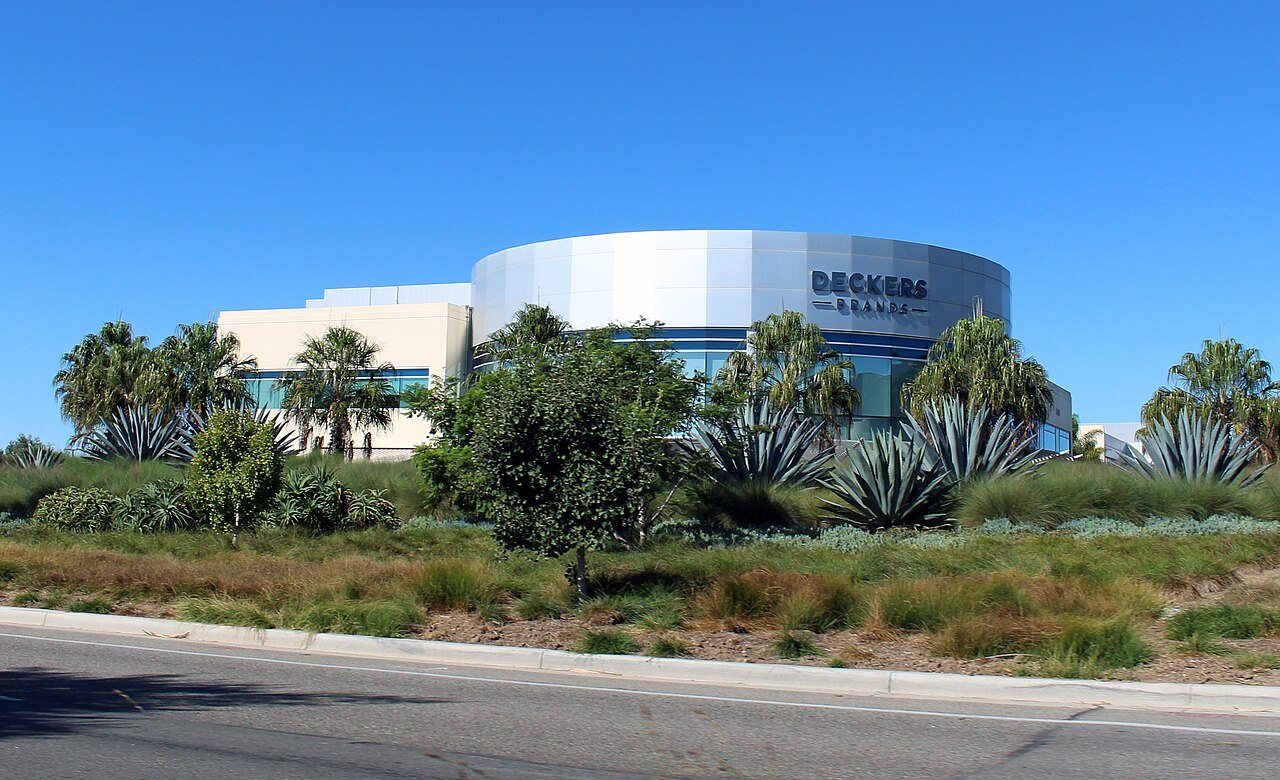
Shares in Deckers Brands fell 8% after the footwear group reported quarterly revenue below market expectations, a top-line miss that outweighed an upgrade to its earnings guidance. The decline in the share price reflects investor disappointment with sales growth at a company whose portfolio includes Ugg and Hoka, even as management signalled stronger profitability ahead.
The company raised its earnings guidance for the period, indicating that margins and cost control are holding up better than the sales trajectory might suggest. But the market focused on the revenue shortfall, which points to softer demand than analysts had forecast. For a consumer-facing footwear business, the top line is the clearest signal of brand momentum, and a miss on that measure tends to weigh more heavily than an improved profit outlook.
Deckers has built its recent growth story on Hoka, the running shoe brand that has expanded rapidly and taken share in the performance footwear market, alongside the long-established Ugg business. The revenue miss raises questions about the pace of that expansion and about consumer spending on premium footwear at a time when household budgets remain under pressure. Investors have been closely watching whether the group can sustain growth rates that made it one of the stronger performers in the sector.
The raised earnings guidance suggests that the company expects to protect profitability even if sales come in softer than hoped. That combination — lower revenue but higher earnings expectations — can reflect a favourable product mix, disciplined discounting, or cost efficiencies. However, it also leaves the company more dependent on margin performance to meet its targets, a position that can be harder to sustain if demand weakens further.
The 8% share price decline places Deckers among the more notable movers in the consumer goods sector following its update. The reaction illustrates how sensitive investors remain to any sign of slowing growth in premium footwear, a category that has benefited from strong brand loyalty and pricing power but is not immune to shifts in consumer confidence. The company's next set of results will be scrutinised for evidence on whether the revenue miss was a one-off or the start of a slower phase.
For now, the update leaves Deckers with a mixed message for the market: profitability is tracking ahead of earlier expectations, but sales are not keeping pace with forecasts. How the company reconciles those two trends over the coming quarters will determine whether the share price reaction proves to be a short-term adjustment or a more lasting reassessment of its growth prospects.
5